11 Jul The Significance of Retirement Planning: Ensuring Peace of Mind in Later Life
Introduction
Retirement is often seen as a long-anticipated reward after decades of dedication to one’s career. It’s the stage where you finally have the freedom to pursue passions, travel, and spend cherished time with loved ones. However, turning these dreams into reality requires more than good intentions; it calls for proactive and robust retirement planning. The financial, emotional, and health-related aspects of life in retirement all require attention to ensure a sense of peace of mind during your golden years. Whether you have many years before retirement or you’re nearing this transition, creating a comprehensive plan is essential for safeguarding your future.
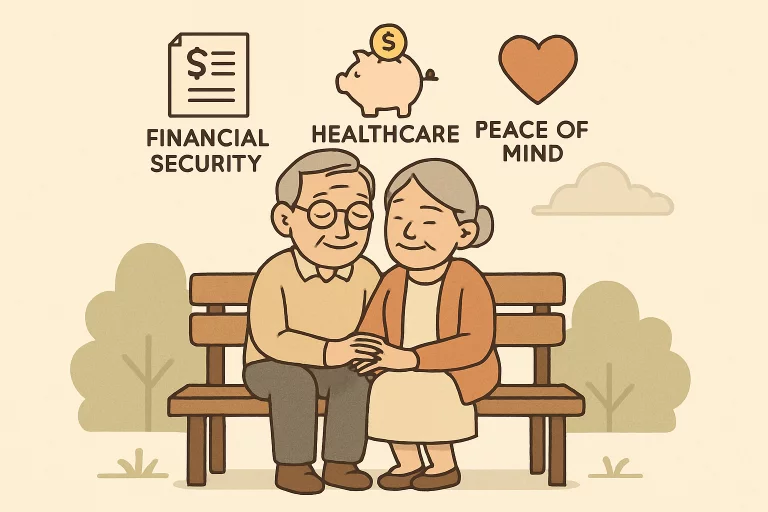
Retirement planning is inherently multifaceted. While building savings is critical, planning encompasses much more: investing wisely, planning for healthcare costs, minimizing tax liabilities, setting legacy goals, and nurturing a purposeful lifestyle. This holistic approach helps retirees achieve not just financial security but also emotional well-being and a sense of fulfillment throughout their later years. The journey to a rewarding retirement begins by recognizing its many dimensions and thoughtfully preparing for them.
Financial Security in Retirement
One of the pillars of a comfortable retirement is dependable financial security. Relying on a single income stream, such as Social Security, can leave you vulnerable to external disruptions or market downturns. Therefore, it’s wise to build a diversified portfolio that draws from employer-sponsored pensions, individual retirement accounts (IRAs), Social Security benefits, personal savings, and even retirement-focused platforms like Retire PR, which offer resources to help plan and manage income strategies effectively. Each source has its pros and cons; pensions may offer stability but limited flexibility, while investment accounts can provide growth potential but demand risk management. By balancing these different avenues, retirees can create a financial safety net that withstands economic shifts, unexpected expenses, and longer lifespans. Taking time to periodically assess your asset allocation, considering both current circumstances and future projections, is fundamental to maintaining financial independence. In addition to diversification, understanding withdrawal rates, spending patterns, and contingency planning is essential to a sound financial strategy. Working with professionals who can tailor your plan to fit your changing needs ensures that your resources will continue to support your lifestyle and ambitions throughout retirement.
Healthcare Considerations
Healthcare is an expense that tends to rise with age, often outpacing inflation and general cost-of-living increases. Planning for medical needs in retirement addresses not only routine healthcare but also the potential need for long-term care—something nearly 70% of older adults may require at some point. Proactively setting aside funds in a Health Savings Account (HSA) while you’re still working, selecting comprehensive insurance coverage, and exploring supplemental plans, such as Medigap, can help protect against catastrophic costs. In addition, considering long-term care insurance can safeguard both your assets and your loved ones from the substantial financial and emotional burden of extended care needs.
Factoring in potential changes in health, prescription medications, and emergencies during planning allows retirees to access the care they need while avoiding unnecessary financial strain. By addressing these needs early, you can foster greater confidence that your retirement plan supports both your well-being and your financial security.
Inflation Protection
Many retirees underestimate the impact that inflation can have on a retirement that may span several decades. Even modest inflation can significantly erode buying power over time, affecting the affordability of essentials such as housing, healthcare, and other daily expenses. Strategic retirement planning incorporates inflation protection by including assets that have historically outperformed inflation, such as stocks, real estate, and Treasury Inflation-Protected Securities (TIPS).
Diversification and regular revisiting of your portfolio are essential for balancing risk and growth. Allocating some investments to growth-oriented vehicles and converting others to stable income generators as you shift through different stages of retirement can help protect your nest egg. Staying vigilant about inflation ensures your savings remain robust enough to support the lifestyle you’ve envisioned, no matter how high the cost of living climbs.
Tax Efficiency
Effective tax planning can make a dramatic difference in the amount of income you have available during retirement. Understanding how your sources of retirement income will be taxed—whether from pre-tax or post-tax accounts, annuities, or Social Security—lets you develop a withdrawal sequence that minimizes taxes and extends the life of your portfolio. Using tax-advantaged accounts (such as Roth IRAs) and strategically timing withdrawals creates more flexibility and may lead to lower required minimum distributions (RMDs) in later years.
Consulting with tax professionals or retirement specialists is advisable for optimizing withdrawal strategies, managing capital gains, and taking advantage of evolving tax laws. This helps preserve more of your hard-earned assets, giving you the freedom to enjoy retirement with fewer financial worries.
Legacy Planning
Legacy planning extends your impact beyond your lifetime, shaping how your assets and values are passed on to those you care about most. This process involves more than just writing a will—it’s about creating a cohesive strategy for asset distribution, appointing trusted individuals to carry out your wishes, and ensuring your intentions are clearly documented. As outlined by Investopedia, legacy planning typically encompasses trusts, beneficiary designations, advance health directives, and powers of attorney, all of which contribute to a comprehensive plan.
Taking the time now to organize these elements brings peace of mind to both you and your loved ones. Clear guidance reduces the likelihood of disputes or confusion and helps support causes that matter to you. Ultimately, legacy planning is an act of love: it’s how you continue helping and protecting others long after you’re gone.
Social Connections and Purpose
Retirement’s rewards aren’t strictly financial. Studies show that retirees who maintain active social lives and a sense of meaning experience improved mental, emotional, and even physical health. Staying connected with friends, family, and community not only combats loneliness but can also enhance happiness and resilience. Retirement presents an ideal opportunity to cultivate new relationships, take up hobbies, volunteer, or pursue educational endeavors that you may have set aside earlier in life.
Nurturing social connections and actively pursuing purpose-driven activities helps safeguard against isolation, a common yet often underestimated risk in later life. A robust retirement plan incorporates these elements alongside financial and healthcare goals, supporting a vibrant and fulfilling daily life.
Professional Guidance
While a wealth of information is available, the complexities of retirement planning can be overwhelming without proper support. Collaborating with a certified financial planner, retirement consultant, or tax advisor ensures your strategy is up-to-date and tailored to your unique objectives. These professionals can help you troubleshoot challenges, adjust your plan as laws or personal circumstances change, and provide relevant insights you might otherwise miss. Their personalized advice makes it easier to prioritize competing goals, reduce risk exposure, and optimize tax strategies—ultimately ensuring a more secure and confident retirement.
Seeking professional guidance doesn’t mean relinquishing control; instead, it empowers you with knowledge and strategies that help make the most of your hard-earned resources.
Conclusion
Retirement planning is a lifelong endeavor with the power to transform later years from a time of worry into a season of opportunity. Addressing financial security, health needs, inflation, taxes, legacy, social engagement, and accessing professional guidance creates a foundation for peace of mind and personal satisfaction. The earlier and more fully you engage with retirement planning, the more empowerment and flexibility you gain.
Sorry, the comment form is closed at this time.