18 Jun Liability Protection: What Every Homeowner Should Know
What Is Liability Coverage?
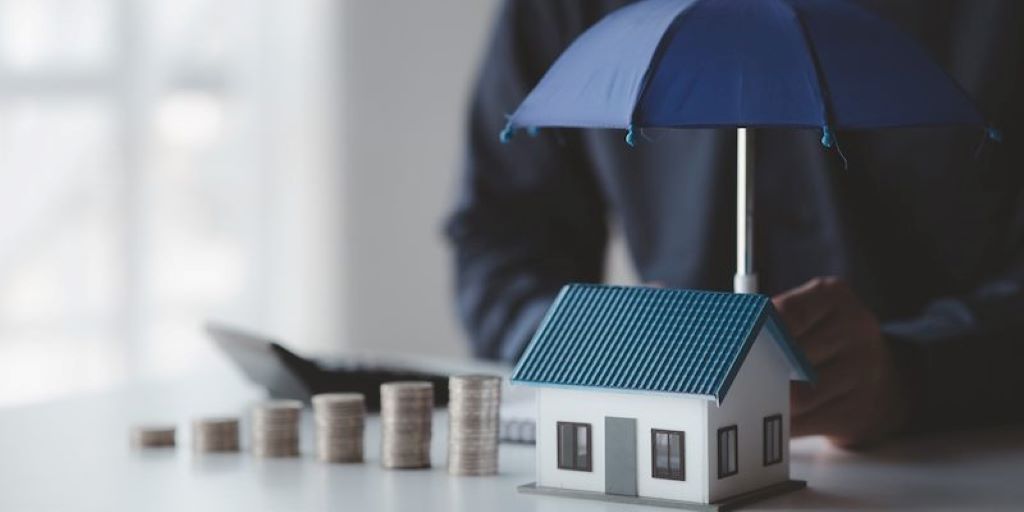
Homeownership brings a sense of security and investment, but it also comes with protecting your household against unforeseen risks. One essential safeguard that every homeowner needs is liability coverage. In simple terms, liability protection is a component of homeowners insurance that helps shield you from financial harm if someone is injured or their property is damaged at your residence, even if you’re not at fault. People often overlook this piece of their policy, focusing primarily on coverage for natural disasters or theft. Yet, when searching for trusted home insurance Newark, DE, or evaluating a new policy, looking for extensive liability protection is vital to ensure you’re covered for life’s unexpected events.
Liability coverage operates as your financial safety net, stepping in when accidents could lead to expensive lawsuits or medical bills. Injuries aren’t confined to your living room or backyard; you could also be responsible for damages caused by you or family members (and often pets) elsewhere. Liability insurance can also offer protection from claims of property damage or bodily injury brought against you by others, even when the incident occurs away from your insured home. This means that coverage travels with you, and that peace of mind can be priceless in a world where legal proceedings are ordinary.
How Does Liability Coverage Work in Home Insurance?
The mechanism behind liability coverage is straightforward but powerful. If a guest or visitor is accidentally harmed on your property—a slip on the stairs, a tumble on an icy walkway, or even a dog bite—your insurance can help cover the following costs. This usually includes medical expenses, legal fees, and any judgments or settlements, up to the maximum amount specified in your policy. Whether the incident happens during a lively backyard barbecue or a simple delivery to your front door, liability insurance is a buffer between an unexpected event and the potential financial aftermath.
Beyond medical costs and legal defense, liability coverage also alleviates the emotional burden of dealing with lawsuits or disputes with neighbors, friends, or delivery personnel. It covers more than single-family houses—renters, condo owners, and landlords reap similar benefits as part of standard coverage or through policy add-ons. Regularly scheduled policy check-ups are key, ensuring you know what’s protected and can make any necessary adjustments.
Common Scenarios Where Liability Coverage Applies
- Dog bites or other animal-related injuries.
- Visitors are slipping and falling on icy or poorly maintained walkways or stairs.
- Injuries sustained by guests during social events, such as pool parties or neighborhood barbecues.
- Property damage caused by your child accidentally breaking a window or a sports ball landing in a neighbor’s garage.
- Trees or large branches from your property falling and damaging a neighbor’s car or structure.
Every day, life is full of scenarios where something could go wrong, and you could be held liable. Liability insurance claims in the U.S. are most frequently related to pet incidents, slips and falls, and property damage from ordinary activities. Even small gatherings or children at play can result in unpredictable, costly accidents. These incidents remind you that accidents can and do happen no matter how careful you are as a homeowner.
What Does Standard Liability Insurance Cover?
Standard personal liability coverage typically focuses on two main areas: bodily injury and property damage. Bodily injury protection takes effect if someone is physically injured on your property—think of trips, falls, or mishaps involving play equipment or swimming pools. Property damage protection extends to accidental harm caused to another person’s belongings, like a wayward baseball breaking a neighbor’s window. Legal representation, defense costs, and settlement fees are usually included, sometimes even if the claim itself is groundless.
For example, if your dog unexpectedly bites a visitor or your child accidentally damages school property, your policy could help cover medical costs or legal claims. Coverage often follows your family members wherever they go, not just at home, providing an extra layer of reassurance for today’s mobile, active lifestyles. Reviewing your policy’s fine print and confirming the exact coverage details is key.
How Much Liability Coverage Do You Need?
Although many standard home insurance policies provide $100,000 to $300,000 in liability coverage, this might not be enough for everyone. Homeowners with valuable assets, high net worth, or increased risk factors—such as a pool, trampoline, or frequent visitors—should consider increasing their coverage. Financial experts generally recommend carrying enough insurance to cover your home, savings, and future wages that might be subject to a lawsuit. In some states, legal judgments can extend beyond your insurance coverage if you are liable for substantial damages.
Your liability needs may change as your lifestyle evolves—whether through home improvements, new pets, or growing families. Annual reviews of your insurance policy, preferably with professional guidance, ensure you remain adequately protected against routine and extraordinary events.
What Isn’t Covered Under Liability Insurance?
Liability insurance, while broad and robust, does have its limits. Most policies exclude incidents stemming from intentional acts or willful misconduct. Injuries to household members and damages tied to home-based businesses are generally not covered; business activities typically require separate business coverage. Many insurers place limits or may not cover injuries related to certain high-risk dog breeds, exotic pets, trampolines, or hazardous home features, sometimes requiring additional riders or endorsements. Carefully reading and understanding your policy’s exclusions section is essential because it outlines scenarios where your coverage could fall short.
For instance, if you operate a business out of your home—a daycare, for example—or frequently host paid events, standard home liability coverage probably won’t apply to those risks. For comprehensive protection, it’s smart to request clarity from your agent and understand your responsibilities as a policyholder.
Optional Enhancements and Umbrella Policies
Personal umbrella insurance is a popular solution for homeowners who need peace of mind beyond standard policy limits. An umbrella policy increases your liability protection—often adding $1 million or more above your base limits—and covers gaps that standard policies don’t. For example, if you’re sued and your homeowners insurance only pays up to $300,000, but the legal judgment is $800,000, your umbrella policy can cover the excess. This type of policy also broadens the scenarios in which you’re protected, sometimes adding worldwide coverage and extending to claims that may otherwise be excluded.
Enhancements can also include specific riders for increased risks, such as additional pet liability or higher pool coverage. Homeowners who frequently entertain, maintain large properties, or have specialized risks should consult an insurance professional to tailor their policy, adding meaningful protection with minimal cost. Often, these upgrades provide significant value for a slight increase in your premium, making them an attractive option in today’s litigious world.
Steps Homeowners Can Take For Better Protection
- Evaluate your property and lifestyle: Consider risky areas such as swimming pools, decks, playground equipment, and pets that could increase liability exposure.
- Review policy limits and exclusions annually: As your assets and liabilities change yearly, examine your insurance documentation to ensure that your coverage reflects your current situation.
- Seek professional advice: Speak with an insurance agent to determine the right amount of liability coverage and discuss options for policy enhancements if needed.
- Maintain your property: Ensure walkways, stairs, and common areas are safe and mark or restrict access to hazardous zones such as pools or construction areas.
- Educate family and guests: Establish and communicate clear house rules about pets, pool use, and equipment safety, reducing risk for everyone involved.
Frequently Asked Questions
- Does liability insurance cover injuries to people living in my house?
- No, liability protection is meant for claims from guests or third parties, not for household members or their healthcare needs.
- Can you increase your liability protection after purchasing a policy?
- Absolutely. Most insurers allow you to modify your coverage limits, add endorsements, or purchase an umbrella policy as your risk exposure grows.
- Is a landlord’s liability policy enough for renters?
- No, renters should obtain liability coverage to protect their interests, since a landlord’s policy only covers the property owner’s risks and legal responsibilities.
Sorry, the comment form is closed at this time.